Author: Molly Haines

  • Should I Sell My Home During the Holidays?

    Should I Sell My Home During the Holidays?

    Selling during the holidays can work well. Fewer homes are listed, so yours faces less competition, and the buyers out shopping in December are usually serious about moving. The tradeoff is fewer buyers overall and a busier calendar, so plan showings and timing with care.

    What are the advantages of a holiday listing?

    • Less competition. Many sellers wait for spring, so buyers have fewer choices.
    • Motivated buyers. People shopping now often have a reason to move, such as a new job or a lease ending.
    • A head start. You can be under contract before the spring rush brings more listings.

    What are the challenges?

    There are fewer buyers overall, and family plans and travel can make showings harder to schedule. Lenders, inspectors and title companies may also be slower around the holidays, so build a little extra time into the closing date.

    How do I make a holiday sale go smoothly?

    • Keep decorations simple so buyers can still see the rooms.
    • Turn on the lights and keep walkways clear and dry on gray days.
    • Agree on showing windows that work around your plans.
    • Price based on what is selling now, since winter buyers watch value closely.

    Thinking about a winter sale?

    See what your home is worth and call Molly at 206-498-4137 to plan your timing.

  • Will New Tariffs Make Homes More Expensive?

    Will New Tariffs Make Homes More Expensive?

    Tariffs mostly affect the cost of building and fixing homes. When materials like lumber, steel, aluminum and appliances cost more, new homes and remodels get more expensive. Prices for existing homes depend more on mortgage rates, local demand and how many homes are for sale.

    How do tariffs reach home prices?

    Builders pay more for imported materials and often pass some of that cost on. Higher costs can also slow how many new homes get built, and less new supply can support prices for existing homes over time.

    What does it mean for buyers?

    New construction may cost more, and so may repairs and upgrades after you buy. Include renovation costs in your budget, and get contractor quotes before you count on a project.

    What does it mean for sellers?

    A home that is already updated and well maintained can stand out when buyers face higher repair and remodel costs. Pre sale projects may cost more, so focus on the fixes buyers value most.

    Have questions about your plans?

    Call Molly at 206-498-4137, search homes for sale, or check your home’s value.

  • What’s Stopping Your Home From Selling?

    What’s Stopping Your Home From Selling?

    If your home is not selling, the reason is usually one of five things: the price, the condition, the photos, how easy it is to see, or a change in the market. The good news is that each one can be fixed once you know which it is.

    What are the most common reasons?

    1. Price. If buyers are touring but not offering, the price is often above what similar homes are selling for.
    2. Condition. Visible repairs, clutter or dated finishes make buyers discount their offers or move on.
    3. Photos and description. Most buyers decide online whether to visit, so weak photos mean fewer showings.
    4. Access. Limited showing times make it hard for buyers to see the home.
    5. The market moved. More competing listings or higher rates can slow sales after you list.

    How do I tell which problem I have?

    Look at the activity. Few online views or showings point to price or photos. Plenty of showings with no offers point to price or condition. Feedback from buyers’ agents often names the issue directly.

    What should I change first?

    Start with the fixes buyers notice most: a price that matches recent sales, fresh photos, simple repairs and easier showing times. Making one clear change is usually better than several small price cuts.

    Want a second opinion on your listing?

    Call Molly at 206-498-4137 or check what your home is worth today.

  • What Is the Best Time of Year to Sell My Home?

    What Is the Best Time of Year to Sell My Home?

    Spring is traditionally the busiest season, with the most buyers and often the strongest prices. But the best time to sell is when your home is ready and the move fits your life. Every season has advantages, and local conditions can matter more than the calendar.

    How does each season compare?

    • Spring: the most buyers and the most competing listings. Homes and gardens show well.
    • Summer: still active, especially for families who want to move between school years.
    • Fall: steadier, with serious buyers who want to settle in before winter.
    • Winter: fewer buyers but far less competition, and the buyers who are looking usually need to move.

    What matters more than the season?

    Your own timing comes first: when you need to move, where you are going next, and whether your home is ready to show. Interest rates and the number of homes for sale in your area also shape how quickly a home sells.

    When should I start preparing?

    Start a few months before you plan to list. That gives you time for repairs, decluttering and photos, so you can launch when the timing is right instead of rushing.

    Want a timeline for your home?

    See what your home is worth today and call Molly at 206-498-4137 to plan the best time to list.

  • What Are the Hidden Costs of Buying a Home?

    What Are the Hidden Costs of Buying a Home?

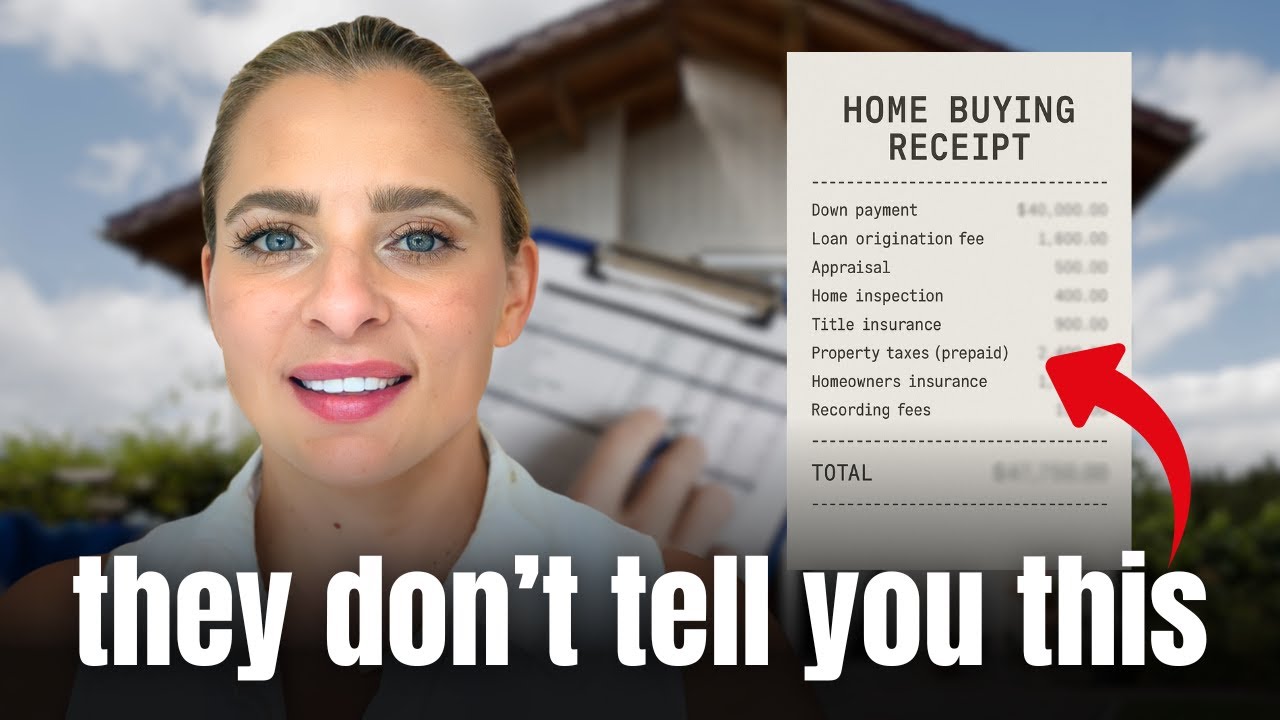
    The down payment is only part of what it costs to buy a home. Buyers also pay closing costs, inspection and appraisal fees, prepaid property taxes and insurance, and moving costs, and then the ongoing costs of owning start. Planning for these up front keeps closing day free of surprises.

    What costs come up before and at closing?

    • Earnest money, a deposit made with your offer that goes toward your purchase.
    • Home inspection and any specialist inspections, such as sewer scope or roof.
    • Appraisal, usually required by your lender.
    • Lender fees for processing and underwriting your loan.
    • Title insurance and escrow fees paid to the title and escrow companies.
    • Prepaid items such as property taxes, homeowners insurance and interest.

    What costs come after I move in?

    Plan for moving, utility setup, HOA dues if the home has them, and regular maintenance. Many owners set aside money each year for repairs, since roofs, water heaters and appliances eventually need replacing.

    How much should I budget for closing costs?

    It depends on your price, loan and lender. Ask your lender for a Loan Estimate early, which lists expected closing costs, and compare estimates from more than one lender.

    Ready to plan your purchase?

    Molly can connect you with trusted lenders and walk you through every cost. Call 206-498-4137 or start your home search.

  • Top Reasons Buyers Cancel a Home Sale

    Top Reasons Buyers Cancel a Home Sale

    Most home sales that fall apart do so for one of a few reasons: the inspection turns up problems, the buyer’s financing falls through, the appraisal comes in low, or the buyer cannot sell their own home in time. Knowing these risks up front helps both sides keep a deal together.

    What are the most common reasons?

    1. Inspection surprises. Roof, foundation, plumbing, electrical or moisture issues the buyer did not expect.
    2. Financing problems. A change in the buyer’s job, credit or debt can stop the loan.
    3. A low appraisal. If the home appraises below the price, the lender will not cover the gap.
    4. Home sale contingency. The buyer’s current home does not sell in time.
    5. Title or disclosure issues. Liens, boundary questions or details the buyer learns late.

    How can sellers prevent a canceled sale?

    Consider a pre listing inspection so there are no surprises, complete your disclosures carefully, and price the home in line with recent sales so it appraises. When offers arrive, look closely at the buyer’s financing and contingencies, not just the price.

    How can buyers protect themselves?

    Get fully preapproved before shopping, avoid new debt or job changes until closing, and read the seller’s disclosures early. Your agent can help you decide which contingencies to keep so you are protected without weakening your offer.

    Want a smoother sale?

    Call Molly at 206-498-4137, check your home’s value, or search homes for sale.

  • Should You Use AI to Price Your Home?

    Should You Use AI to Price Your Home?

    AI and online estimates are a fine place to start, but they should not set your list price on their own. They work from public records and recent sales, so they cannot see your remodel, your view, your layout or the condition of your home. Use the estimate as a range, then get a local pricing review before you list.

    How do automated estimates work?

    Automated valuation tools compare your home’s public details, such as square footage, bedrooms, lot size and past sale price, with nearby sales. Newer AI tools add more data and can update quickly, but they still rely on what is in the records.

    What do they miss?

    • Updates and remodels that are not in public records.
    • Condition, finishes and deferred maintenance.
    • Views, street noise, privacy and the feel of the lot.
    • How buyers are responding to similar homes right now.

    Why do different sites show different values?

    Each tool uses its own data and formula, so the same home can show noticeably different numbers. That spread is a reminder that an estimate is a range, not a price.

    What is the best way to use them?

    Check an estimate to get a ballpark, then ask a local agent to walk through your home and compare it with active, pending and recently sold homes nearby. That review turns a range into a list price you can defend to buyers.

    Ready for a real number?

    Start with a free instant estimate, then call Molly at 206-498-4137 for a personal review.

  • How Do Fed Rate Cuts Affect Buyers and Sellers?

    How Do Fed Rate Cuts Affect Buyers and Sellers?

    When the Federal Reserve cuts its rate, mortgage rates do not automatically drop by the same amount. Mortgage rates follow the bond market and expectations about inflation, so they often move before the Fed acts. A cut can still help buyers by easing borrowing costs over time, and it can bring more buyers back into the market.

    Does a Fed cut lower mortgage rates?

    Not directly. The Fed sets a short term rate that banks charge each other. Thirty year mortgage rates track longer term bond yields more closely, which react to the economy and to what investors expect the Fed to do next. That is why rates sometimes fall before a cut and rise after one.

    What does a rate cut mean for buyers?

    Lower rates can mean a lower monthly payment or more buying power. They can also bring more buyers back, which can mean more competition for the best homes. Many buyers focus on finding the right home and plan to refinance if rates drop meaningfully later.

    What does it mean for sellers?

    Falling rates usually widen the pool of buyers who can afford your home, which can support demand and pricing. Sellers who are also buying benefit on the purchase side too.

    Should I wait for rates to drop?

    Timing rates is hard, and waiting can mean facing higher prices or more competition. A lender can show you what today’s rate means for your payment, and an agent can show you what is happening with prices nearby.

    Want to talk through your timing?

    Call Molly at 206-498-4137, search homes for sale, or check your home’s value.

  • How to Use a Bridge Loan to Buy a New Home Before Selling

    How to Use a Bridge Loan to Buy a New Home Before Selling

    A bridge loan is a short term loan that uses the equity in your current home to help you buy your next one before the first home sells. It can let you make an offer without a home sale contingency, which makes your offer more attractive to sellers.

    How does a bridge loan work?

    The lender advances money against the equity in the home you own, and you use it toward the down payment on the new home. When your current home sells, the sale proceeds pay off the bridge loan. These loans usually run for months, not years.

    Who is a bridge loan good for?

    It suits homeowners with solid equity who have found their next home and do not want to wait or move twice. It is common for move up buyers and for people downsizing who want to settle into the new place before listing.

    What are the costs and risks?

    • Bridge loans often carry higher rates and fees than a standard mortgage.
    • You may carry two housing payments until the first home sells.
    • If your home takes longer to sell than planned, the costs add up.

    What are the alternatives?

    Ask your lender to compare a bridge loan with a home equity line of credit, an offer contingent on selling your home, or selling first and renting for a short time. The right choice depends on your equity, your income and how competitive the market is.

    Planning a move up or a downsize?

    Molly can help you time the purchase and the sale and connect you with trusted lenders. Call 206-498-4137, check your home’s value, or search homes for sale.

  • How Should You Respond to a Lowball Offer on Your Home?

    How Should You Respond to a Lowball Offer on Your Home?

    When a low offer arrives, do not ignore it and do not take it personally. Look at the full offer, including terms, and respond with a counteroffer backed by recent sales. A buyer who makes any offer is interested, and a thoughtful counter often turns a low start into a workable deal.

    Should I reject a low offer outright?

    Usually not. Rejecting it ends the conversation, while a counter keeps the buyer engaged. Even if you hold close to your price, a counteroffer tells the buyer you are willing to talk.

    What should I look at besides the price?

    • Financing: is the buyer preapproved, and how much are they putting down?
    • Contingencies: inspection, financing, appraisal or the sale of their own home.
    • Timing: the closing date and whether it fits your plans.
    • Requests: closing cost credits, repairs or items they want included.

    A lower price with strong terms can sometimes be worth more to you than a higher price with risky ones.

    How do I make a strong counteroffer?

    Base your counter on recent comparable sales and share that data with the buyer’s agent. You can also trade on terms, such as a quicker close or fewer contingencies, instead of price alone.

    Do several low offers mean my price is too high?

    It can. If several buyers come in low, or showings are steady but no one offers, the market may be telling you the price needs another look.

    Need help reviewing an offer?

    Call Molly at 206-498-4137 or check what your home is worth today.